Will the midterm election have profound impacts on interest rates and real estate prices? Historically, divided governments have often been great for real estate with declining mortgage rates which in turn lead to higher sales volumes. Will history repeat with this cycle or has something fundamentally changed? How will the midterms impact mortgage rates and real estate prices?
How have interest rates historically been impacted by a divided government?
Historically a divided government has led to declining interest rates as fiscal discipline of one party or the other kept a cap on huge government spending. This will likely be initial market reaction which should lead to a small drop in rates. I would recommend taking advantage of this window as I think it will be short lived.
Unfortunately history is unlikely to repeat itself as both parties are playing to populist arms of their respective parties to become the spending party.
Long term, we are in for a ride. Schroders economics had an interesting take: The likely fault lines are already visible. Republicans want higher defense spending while Democrats want to reverse cuts to Medicaid in the administration’s One Big Beautiful Bill. Given the increasingly confrontational nature of fiscal negotiations in recent years, neither side may be willing to concede much ground. A last-minute compromise could therefore accommodate both demands rather than force either side to retreat. By our estimates, this could widen the deficit by around 1% of GDP.
The above sounds plausible as neither party seems to be the party of fiscal discipline as deficits continue expanding under both parties.
Does the federal reserve control interest rates?
First, it is important to note that the federal reserve does not directly control mortgage rates. The fed controls the “federal funds rate”. The federal funds rate is the rate at which banks and credit unions lend reserve balances to other banks and credit unions overnight. In a nutshell this is the rate banks get on the money they are holding in cash/reserves. Here is a more detailed explanation from Wikipedia .
So how are mortgage rates set? Unfortunately, mortgage rates are not “set”. There is no government or private party that can set rates per se. Mortgage rates are typically based on the 10-year treasury yield. So how does this work?
Before discussing rates, it is important to understand how bond yields work. The most important piece of this equation is the relationship between a bond price and its return. For treasuries, it is critical to note that a bond price and its yield move in inverse. What this means is that a higher bond price results in a lower yield and vice versa where a higher yield results in a lower bond price. For simplification purposes, I will not get into the full details of why bonds function the way that they do. Rest assured that it works this way and will always work this way.
With this key piece of information, we can now understand why mortgages do not move in direct correlation with the federal funds rate.
Will the midterm elections cause interest rates to increase.
Yes, both parties seem to be the spending party with no fiscal discipline. This has led to huge deficits that continue to grow under both parties’ leadership. Unfortunately, the recent midterms do not seem to change the current trajectory which will lead to higher deficits and in turn the sale of more bonds to finance the debt.
We can look no further than many of the Democratic priorities that will restore cuts to Medicare, food stamps, etc… all of which will add huge sums to the deficit.
Basic economics tells us that increases in supply without a tandem increase in demand will lead to lower prices. As stated above as bond prices drop, yields and in turn interest rates will increase substantially.
How will higher mortgage rates impact real estate prices and real estate volumes?
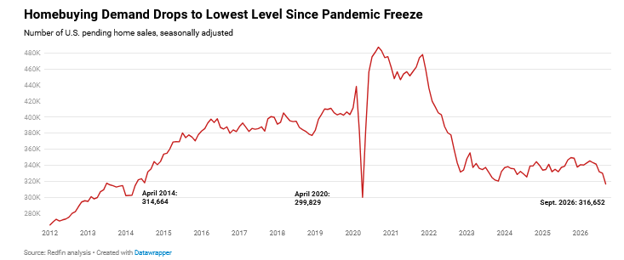
We have already seen over the last several years real estate volumes falling to historic lows throughout the country. For the first time in three years, pending home sales declined in all 50 of the most populous U.S. metros. The last time that happened was September 2023, which was also the last time mortgage rates surpassed 7% for a sustained period.
The declines were biggest on the West Coast: Seattle posted the biggest drop (-24.4% year over year), followed by Los Angeles (-16%), San Diego (-15.8%) and Anaheim, CA (-15.5%). Those Southern California metros are among the priciest in the U.S., so rising mortgage rates hit them hard, pricing many on-the-fence buyers out.
Look for this trend to continue as rates stay higher for longer and possibly increase due to deficits. Currently the market is having a game of chicken with sellers deciding to wait out the market and buyers demanding huge price drops. Unfortunately I don’t see a huge change in the market standoff.
Do the midterm election results increase the risk of a larger correction?
With both parties spending like crazy and no fiscal discipline, the probability of a larger market reset is amplified. The bond market does not like uncertainty and with no plan for a balanced budget the market is going to require a risk premium for US Treasuries which ultimately could raise rates high enough to trigger a correction/recession.
Will the midterms help real estate the remainder of the year?
Unfortunately, the midterms do not solve the current real estate crisis we are in with anemic volumes and prices flat to declining in most markets. The best-case result from the midterms will be a “stuck market” like we are currently in, but a worse-case scenario is beginning to emerge which would be a larger correction/recession due to increasing deficits.
Until our politicians from both parties understand that money doesn’t grow on trees we will have substantial pain ahead. We are seeing this play out in economies throughout Europe as debt soars a percentage of GDP until it becomes unsustainable. Unfortunately, under both parties the US is on a collision course with the bond market and it likely will not end well.
Where I learn more about the midterm impact on real estate prices and interest rates?
- https://www.schroders.com/en-us/us/institutional/insights/us-midterms-can-the-democrats-retake-both-houses-and-what-would-that-mean-for-investors-/
- https://www.redfin.com/news/pending-home-sales-sink-rates/
- https://www.fairviewlending.com/will-house-prices-increase-or-are-we-set-for-a-reset/
- https://www.fairviewlending.com/will-house-prices-rise-and-defy-all-odds/
- https://www.fairviewlending.com/federal-reserve-raises-rates-yet-mortgage-rates-fall-why/
We are a Private/ Hard Money Lender funding in cash!
If you were forwarded this message, please subscribe to our newsletter
Glen Weinberg personally writes these weekly real estate blogs based on his real estate experience as a lender and property owner. I’m not an armchair reporter/writer. We are an actual private lender, lending our own money. We service our own loans and own commercial and residential real estate throughout the country.
My day job is and continues to be private real estate lending/ hard money lending which enables me to have a unique perspective on the market. I don’t accept any paid sponsorships or ads on my blog to ensure accurate information. I’ve been writing this for almost 20 years and have over 30k subscribers. Please like and share my blogs on linkedin, twitter, facebook, and other social media and forward to your friends 😊. I would greatly appreciate it.
Fairview is a hard money lender specializing in private money loans / non-bank real estate loans in Georgia, Colorado, and Florida. We are recognized in the industry as the leader in hard money lending/ Private Lending with no upfront fees or any other games. We fund our own loans and provide honest answers quickly. Learn more about Hard Money Lending through our free Hard Money Guide. To get started on a loan all we need is our simple one page application (no upfront fees or other games). Learn how to find a reputable hard money lender and why Fairview is the best hard money lender for investors.
Written by Glen Weinberg, COO/ VP Fairview Commercial Lending. Glen has been published as an expert in hard money lending, real estate valuation, financing, and various other real estate topics in Bloomberg, Businessweek ,the Colorado Real Estate Journal, National Association of Realtors Magazine, The Real Deal real estate news, the CO Biz Magazine, The Denver Post, The Scotsman mortgage broker guide, Mortgage Professional America and various other national publications.