It is a bit perplexing; mortgage rates are over 7%, well over double their lows, and yet real estate prices are once again heading higher after a minor pullback late last year. Prices have pivoted from last fall to make a strong comeback and approach new highs. What is driving the recent rise in prices? Is this sustainable? What does this mean for inflation?
What was in the Case Schiller data?
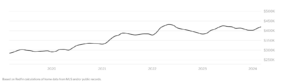
The S&P CoreLogic Case-Shiller National Home Price Index reaccelerated and grew by 6.4% year over year in February, marking the index’s eighth straight month of annual growth.
The increase, which was up from 6.0% one month prior, was the fastest yearly rise since November 2022. Home prices nationwide are now largely at or near all-time highs again after some short-term decline last year. Prices are now up by 1.3% compared to the recent high in June 2022.
“Since the previous peak in prices in 2022, this marks the second time home prices have pushed higher in the face of economic uncertainty,” said Brian D. Luke, head of commodities, real & digital assets at S&P Dow Jones Indices. “The first decline followed the start of the Federal Reserve’s hiking cycle. The second decline followed the peak in average mortgage rates last October. Enthusiasm for potential Fed cuts and lower mortgage rates appears to have supported buyer behavior, driving the 10- and 20-city composites to new highs.”
Why are home prices now rising again?
- Lock in effect: there is still limited inventory due to low rates “locking in “ homeowners
- Strong labor market wage gains: Labor market remains robust which continues to drive spending
- Very few defaults/distress in residential: With a strong labor market and locked in low rates, the distress in the market is very low/non existent
- Extremely high building costs: As labor rates and materials continue to increase coupled with higher land costs in desirable areas building costs have increased substantially. This means that house prices also will be higher as to buy a “replacement” will be expensive. Furthermore, the high building costs are making it difficult to build affordable units which is further driving up prices especially on the affordable end of the price curve.
Take the recent data with a grain of salt
Although there are several factors continuing to drive up costs, I would take the recent data with a grain of salt. During the first 5 months of the year sales are usually softer than the spring/summer season. Remember there is also a lag as a house could go under contract but not close for 30-60 days. At the end of the summer, we will have a much better feel on pricing.
Are the price gains sustainable?
In the short term the price gains might continue a bit longer, but long term they are not sustainable. Here are the primary drivers that will eventually change the tide on house appreciation.
- High rates will eventually break the market
- Labor market must correct
- Lock in effect will eventually fade
The Federal reserve has continued to emphasize higher for longer and interest rates have been hovering between 7-7.5%. At these rates, income gains cannot keep up with the increased costs. Higher rates will eventually slow down the residential real estate market. Furthermore, the longer rates stay higher, the more likelihood that unemployment increases which will lead to more inventory due to distress.
Will house prices continue higher?
It is important to remember that housing makes up about 30% of the consumer price index. For the CPI to fall to the federal reserve’s target, there must be a major change in housing. Currently housing is continuing to appreciate leading to increases in the CPI. To reverse the inflation increases, the federal reserve has vowed to keep rates higher for longer.
Although we are not seeing any impact of rates on the housing market yet, it will eventually happen. As rates remain high, financial stress will ultimately filter through the economy from a slow down in spending, to higher unemployment, to less business investment, etc… Each of these items will eventually place downward pressure on prices.
We aren’t seeing much if any financial stress in the economy today, but storm clouds are brewing. Look for prices to come off their highs later this year as higher for longer rates finally slow things down.
Additional Reading/Resources
- https://www.cnbc.com/2024/04/30/sp-corelogic-case-shiller-home-prices-index-february.html
- https://www.fairviewlending.com/why-are-mortgage-rates-rising-again/
- https://www.fairviewlending.com/clearest-sign-yet-commercial-real-estate-is-in-big-trouble/
- https://coloradohardmoney.com/colorado-property-values-soften-property-taxes-increased-36-82/